BankUnited
Why banks are valued on price-to-tangible-book versus peers and recent deals, and how loan runoff creates an EPS trough.
- Rating
- Price target
- USD 33.00
- Published
- February 5, 2015
- Length
- 30 pages
- Sector
- Regional banks
- Market
- US
What the analyst argued
Barclays initiated BankUnited at Overweight, framing a 2015 EPS dip as a buying opportunity: high-yielding FDIC-covered loans acquired from a failed Florida thrift were running off, but new loan growth (a 44% CAGR since 2011) had just overtaken them in interest income for the first time, so EPS should rebound in the second half. The bank's Miami and New York footprint, CEO John Kanas's record, and M&A optionality supported the case. At 1.5x tangible book versus a 1.7x peer and deal average, the $33 target assumed the discount closed as EPS compounded at 12% through 2017.
Lead analysts: Matthew J. Keating, Jason M. Goldberg.
Inside the report
- 01Business Model Analysis (SWOT)
- 02Business & branch overview
- 03Investment positives
- 04Operates in attractive markets with ample growth runway
- 05Franchise investments paying off
- 06Investment risks
- 07Near-term EPS trough
- 08Valuation
- 094Q14 EPS review
- 10Income statement and balance sheet
- Price-to-book
- P/E
- Comparable companies
- Precedent transactions
Includes a multi-year earnings model with the income statement, balance sheet, and cash flow forecasts the valuation is built on.
Read the report
30 pages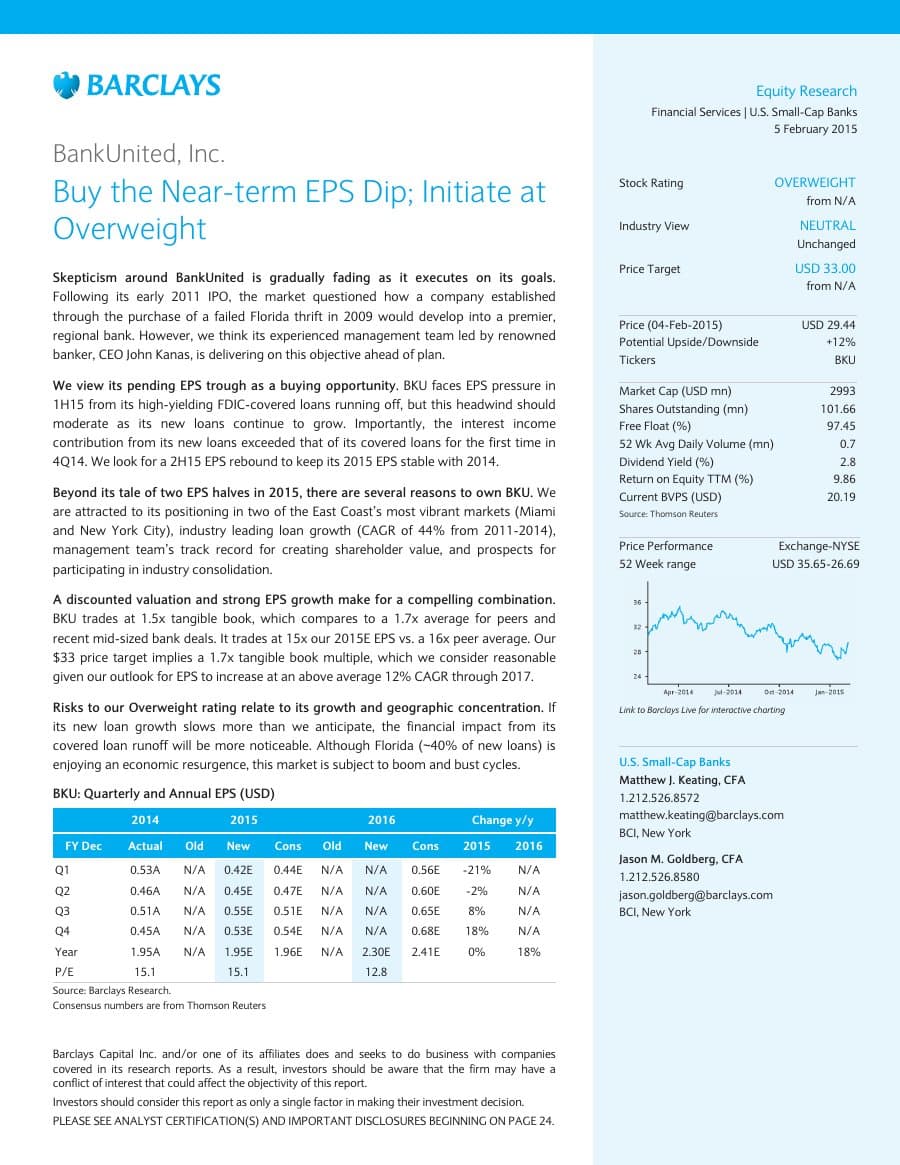 Tap the cover to open the PDF.
Published by Barclays on February 5, 2015 and hosted here for educational use; the report and everything in it belongs to Barclays. The rating, estimates, and price target are the analysts’ view on that date, more than a decade ago, and are not a recommendation today. Copy first uploaded October 5, 2026.
More initiations
20 reports in the library- VA Tech WabagNomuraHow to size a top-down market opportunity (national water infrastructure) and choose a P/E benchmark when a company lacks direct listed peers.Initiation of coverage · January 27, 2015 · 42 pagesTarget INR 1,958
- Australian Aged CareDeutsche BankHow a sector initiation models demographics and government funding before comparing three operators on the same DCF framework.Sector initiation · January 23, 2015 · 126 pagesTarget AUD 5.90 Estia, 4.50 Regis, 2.12 Japara
- 3P LearningDeutsche BankHow to value a recently listed subscription software company with a DCF, then stress-test it with bull and bear scenarios.Initiation of coverage · January 14, 2015 · 44 pagesTarget AUD 2.70
- Achillion PharmaceuticalsBarclaysHow a biotech analyst values a pre-revenue drug pipeline with a risk-adjusted NPV sum-of-the-parts and a competitive launch timeline.Initiation of coverage · March 3, 2015 · 23 pagesTarget USD 8.00