Achillion Pharmaceuticals
How a biotech analyst values a pre-revenue drug pipeline with a risk-adjusted NPV sum-of-the-parts and a competitive launch timeline.
- Rating
- Price target
- USD 8.00
- Published
- March 3, 2015
- Length
- 23 pages
- Sector
- Biotech
- Market
- US
What the analyst argued
Barclays initiated Achillion at Underweight with an $8 target despite encouraging early hepatitis C data, because the market had fundamentally changed: Gilead, Merck and AbbVie were launching all-oral regimens with 6-8 week cures, the eligible US patient pool was shrinking, and discounting to win share no longer worked. Even a successful 2018 launch with ~$1B peak sales, valued by a risk-adjusted NPV sum-of-the-parts, left the stock 35% above fair value. A takeout was seen as the main upside but less likely given the market dynamics.
Lead analysts: Geoff Meacham, Michael Ulz.
Inside the report
- 01Investment Thesis
- 02Risks to Rating and Price Target
- 03Valuation (NPV Sum-of-the-Parts)
- 04Executive Summary
- 05Upcoming Milestones
- 06Key Fundamental Considerations: Hepatitis C Treatment Landscape
- 07Development Strategy
- 08Competitive Landscape
- 09Financial Outlook
- 10Appendix: Senior Management
- Sum-of-the-parts
- Comparable companies
Includes a multi-year earnings model with the income statement, balance sheet, and cash flow forecasts the valuation is built on.
Read the report
23 pages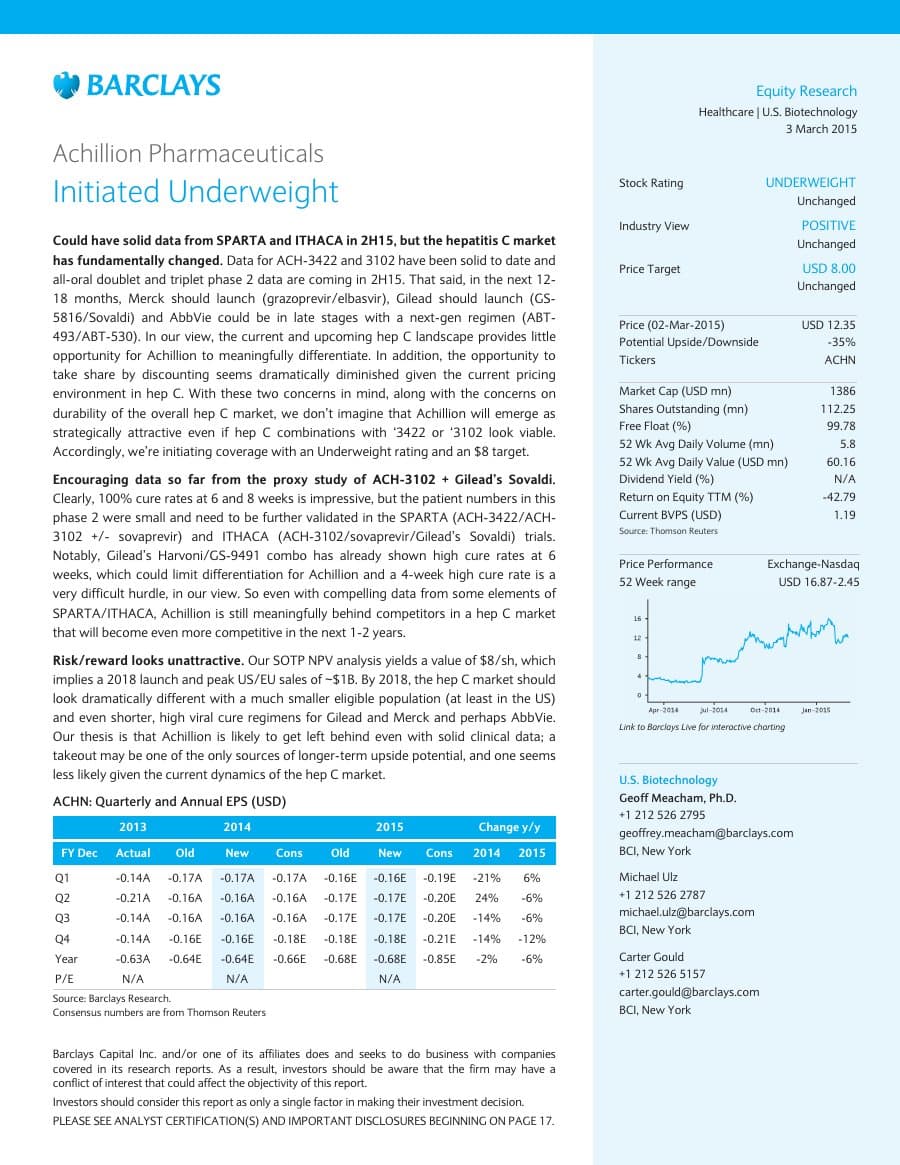 Tap the cover to open the PDF.
Published by Barclays on March 3, 2015 and hosted here for educational use; the report and everything in it belongs to Barclays. The rating, estimates, and price target are the analysts’ view on that date, more than a decade ago, and are not a recommendation today. Copy first uploaded October 5, 2026.
More initiations
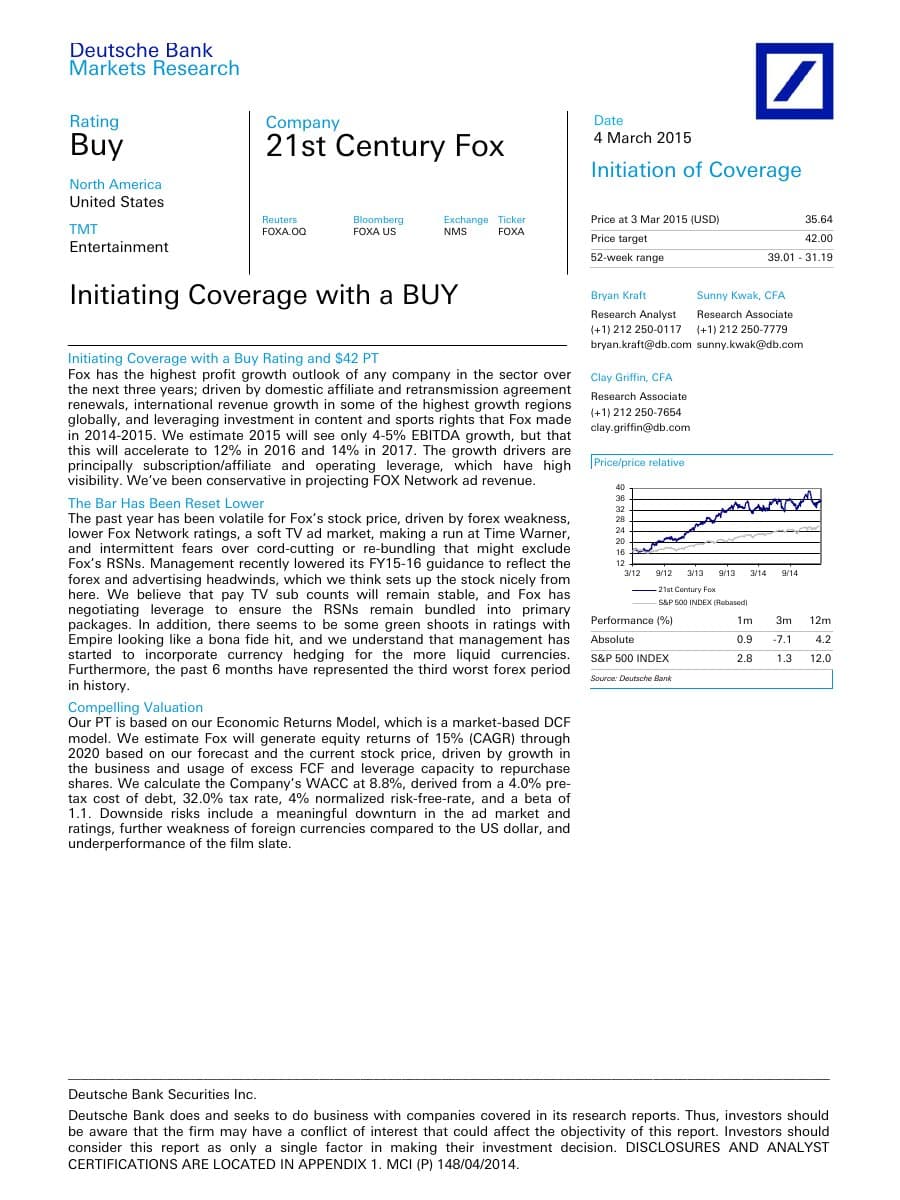
20 reports in the library- 21st Century FoxDeutsche BankHow Deutsche Bank's Economic Returns Model, a market-based DCF, turns a WACC and a free cash flow yield into an implied equity return.Initiation of coverage · March 4, 2015 · 17 pagesTarget USD 42.00
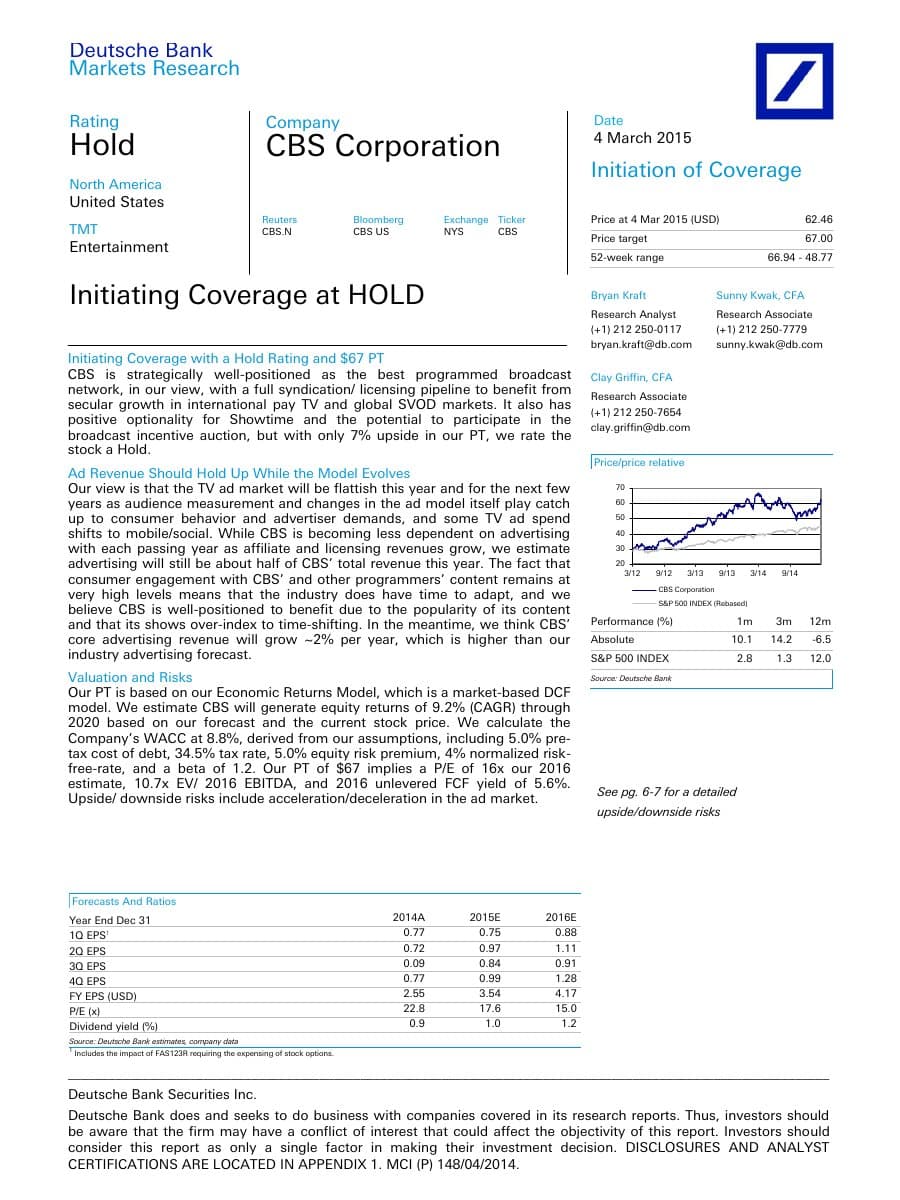
- CBSDeutsche BankHow the same valuation framework yields a Hold when upside to target is only 7%, and how ad exposure caps a broadcaster's multiple.Initiation of coverage · March 4, 2015 · 16 pagesTarget USD 67.00
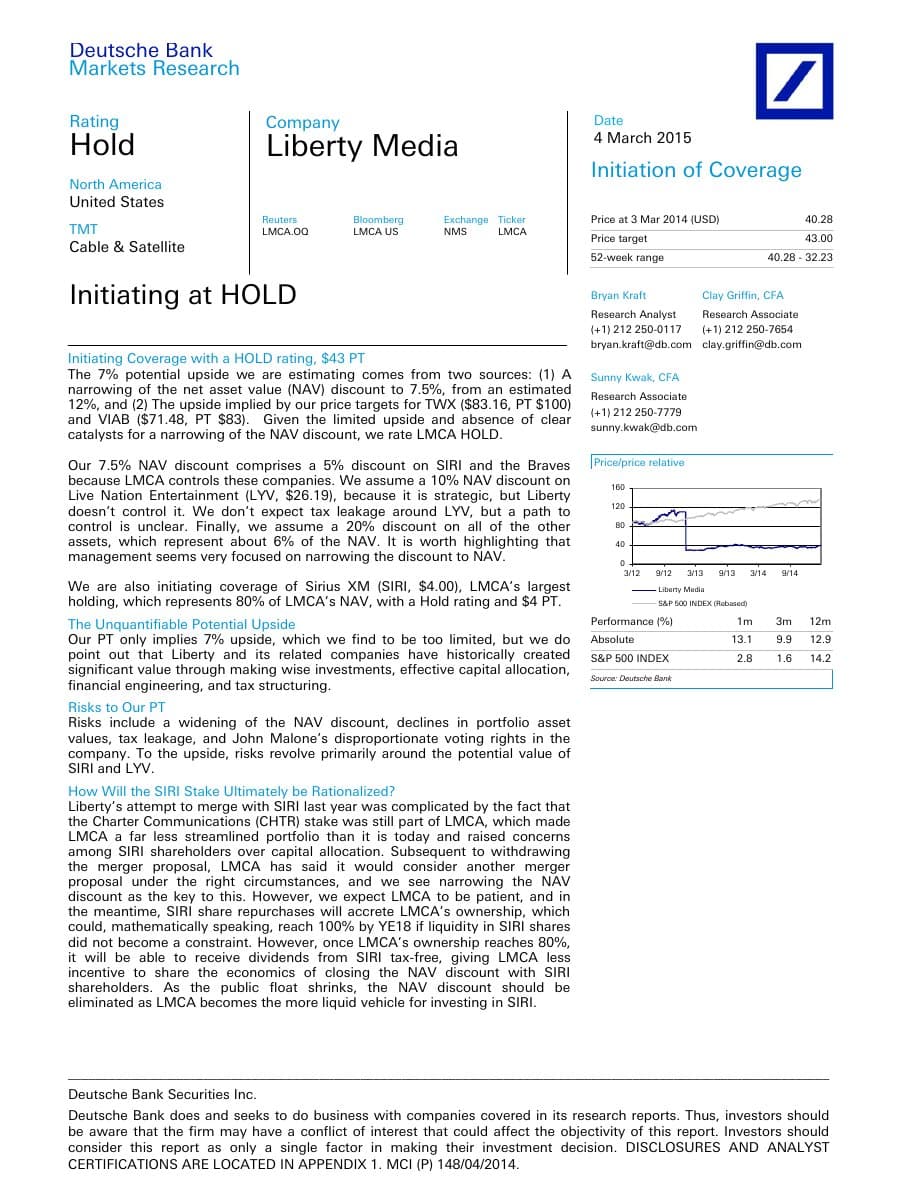
- Liberty MediaDeutsche BankHow to value a holding company by summing its stakes at a discount to net asset value based on control and liquidity.Initiation of coverage · March 4, 2015 · 11 pagesTarget USD 43.00
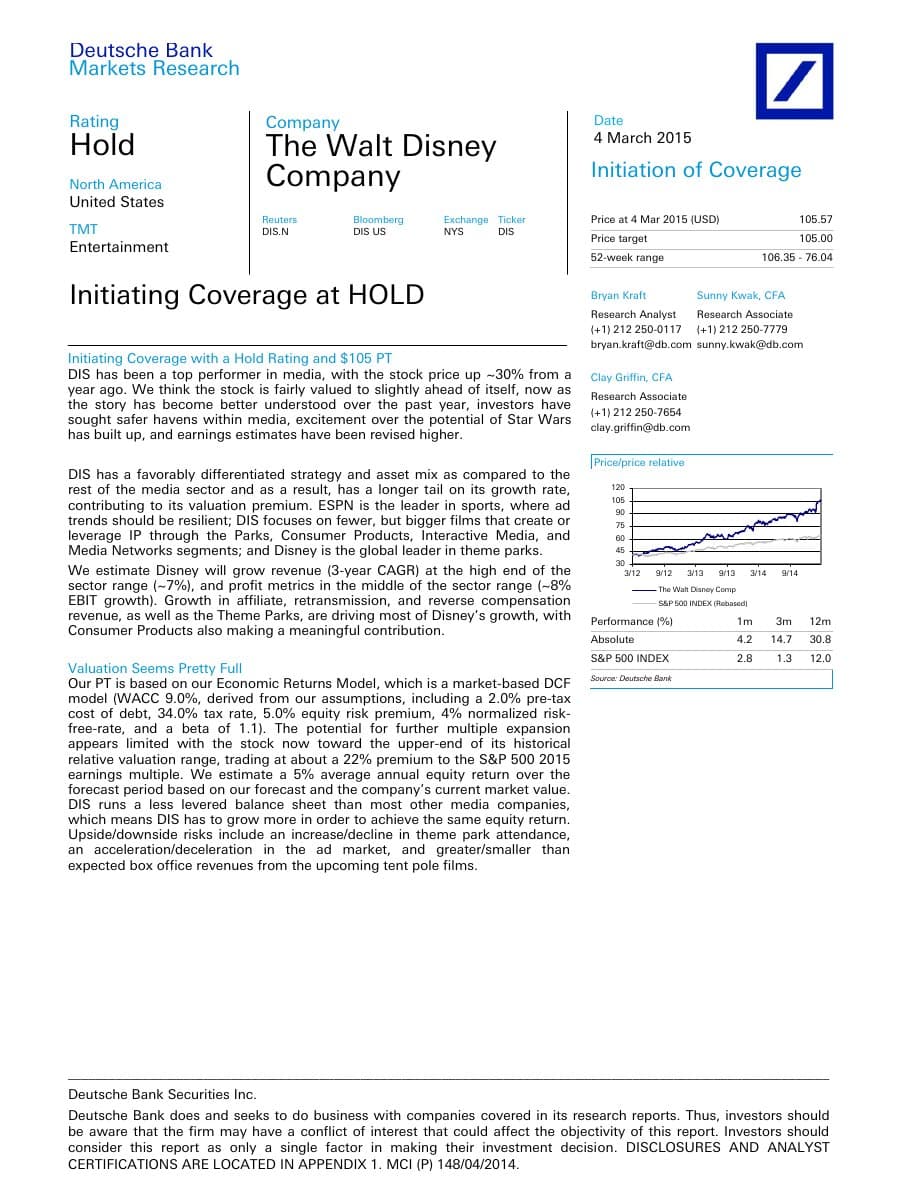
- Walt DisneyDeutsche BankWhy a great company can still be a Hold: separating business quality from valuation and expected equity return.Initiation of coverage · March 4, 2015 · 18 pagesTarget USD 105.00