Walt Disney
Why a great company can still be a Hold: separating business quality from valuation and expected equity return.
- Rating
- Price target
- USD 105.00
- Published
- March 4, 2015
- Length
- 18 pages
- Sector
- Media & Entertainment
- Market
- US
What the analyst argued
Deutsche Bank initiated Disney at Hold with a $105 target against a $105.57 price, judging a stock up 30% in a year to be fairly valued to slightly ahead of itself as investors sought safe havens in media and Star Wars excitement built. The analysts admired Disney's differentiated mix (ESPN's sports leadership, a fewer-but-bigger film strategy that feeds Parks and Consumer Products, and global theme-park leadership) and forecast revenue growth at the high end of the sector. But the Economic Returns Model (9.0% WACC) implied only a 5% annual equity return, and the 22% P/E premium to the S&P 500 left little room for multiple expansion.
Lead analysts: Bryan Kraft, Sunny Kwak, Clay Griffin.
Inside the report
- 01Investment Thesis
- 02Outlook
- 03Valuation
- 04Risks
- 05Company Analysis: Disney's Strategy and Asset Mix Is Different from the Rest of the Media Sector
- 06ABC Is Light on Sports, But Still a Leader in Entertainment
- 07Revenue growth rates by segment
- 08Margin outlook (Parks, Studio)
- 09Comparable Company Valuations
- 10Income Statement, Balance Sheet, Cash Flow Statement
- DCF
- P/E
- EV/EBITDA
- Comparable companies
Includes a multi-year earnings model with the income statement, balance sheet, and cash flow forecasts the valuation is built on.
Read the report
18 pages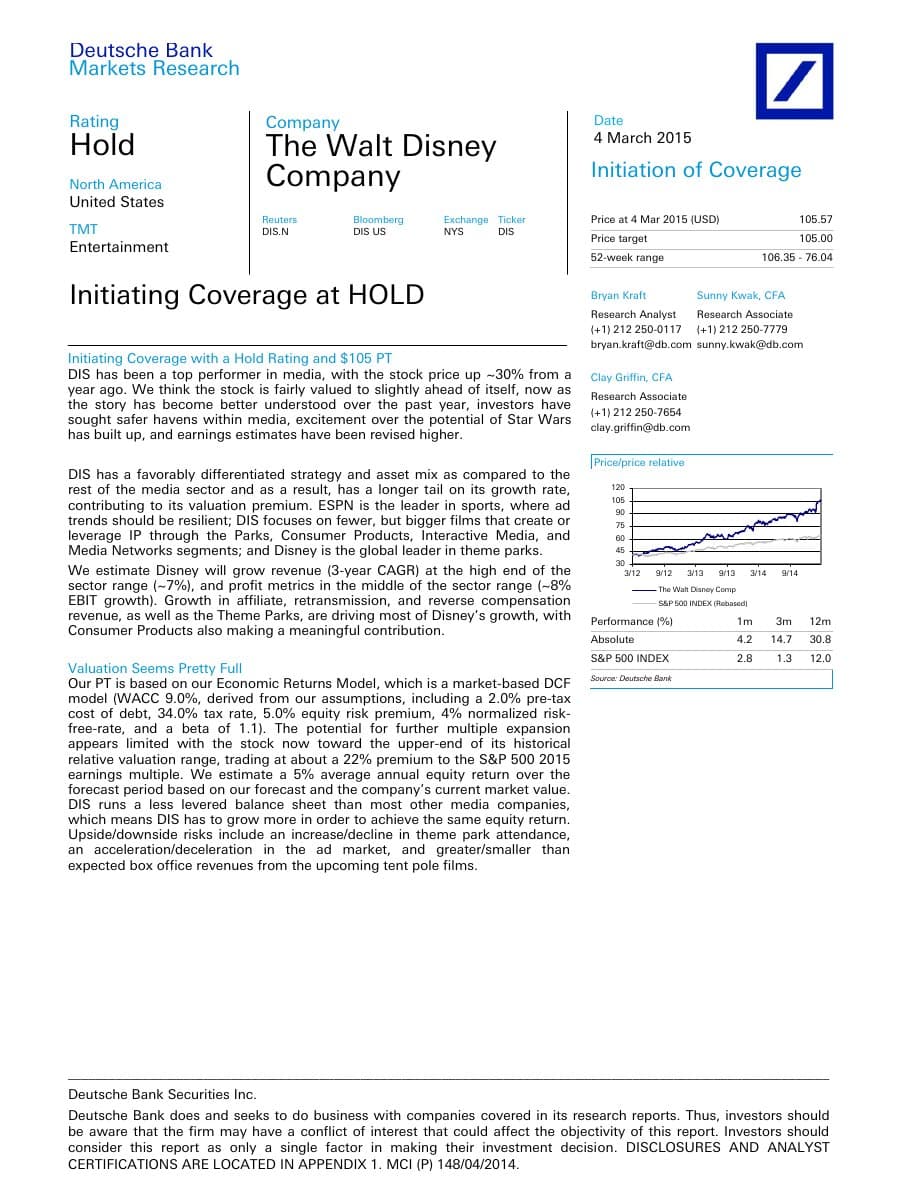 Tap the cover to open the PDF.
Published by Deutsche Bank on March 4, 2015 and hosted here for educational use; the report and everything in it belongs to Deutsche Bank. The rating, estimates, and price target are the analysts’ view on that date, more than a decade ago, and are not a recommendation today. Copy first uploaded October 5, 2026.
More initiations
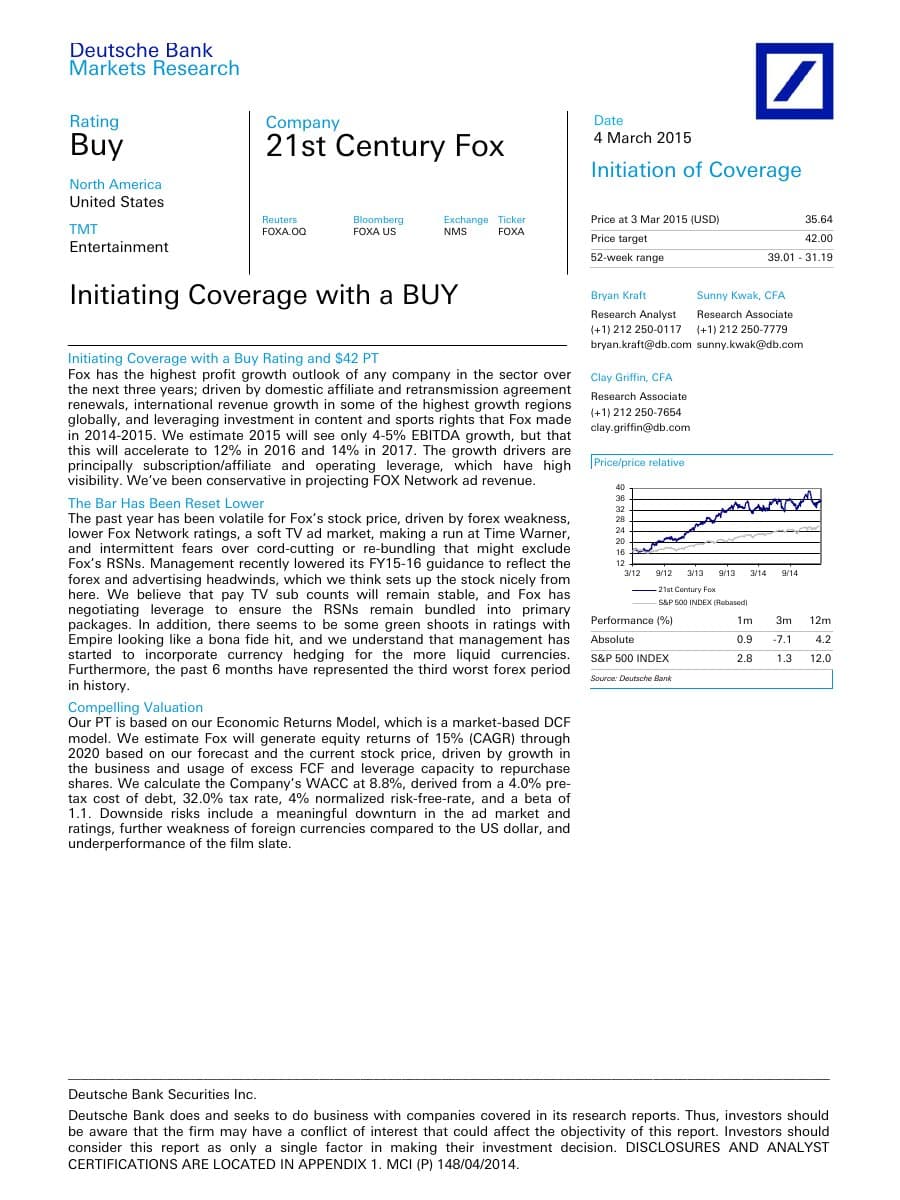
20 reports in the library- 21st Century FoxDeutsche BankHow Deutsche Bank's Economic Returns Model, a market-based DCF, turns a WACC and a free cash flow yield into an implied equity return.Initiation of coverage · March 4, 2015 · 17 pagesTarget USD 42.00
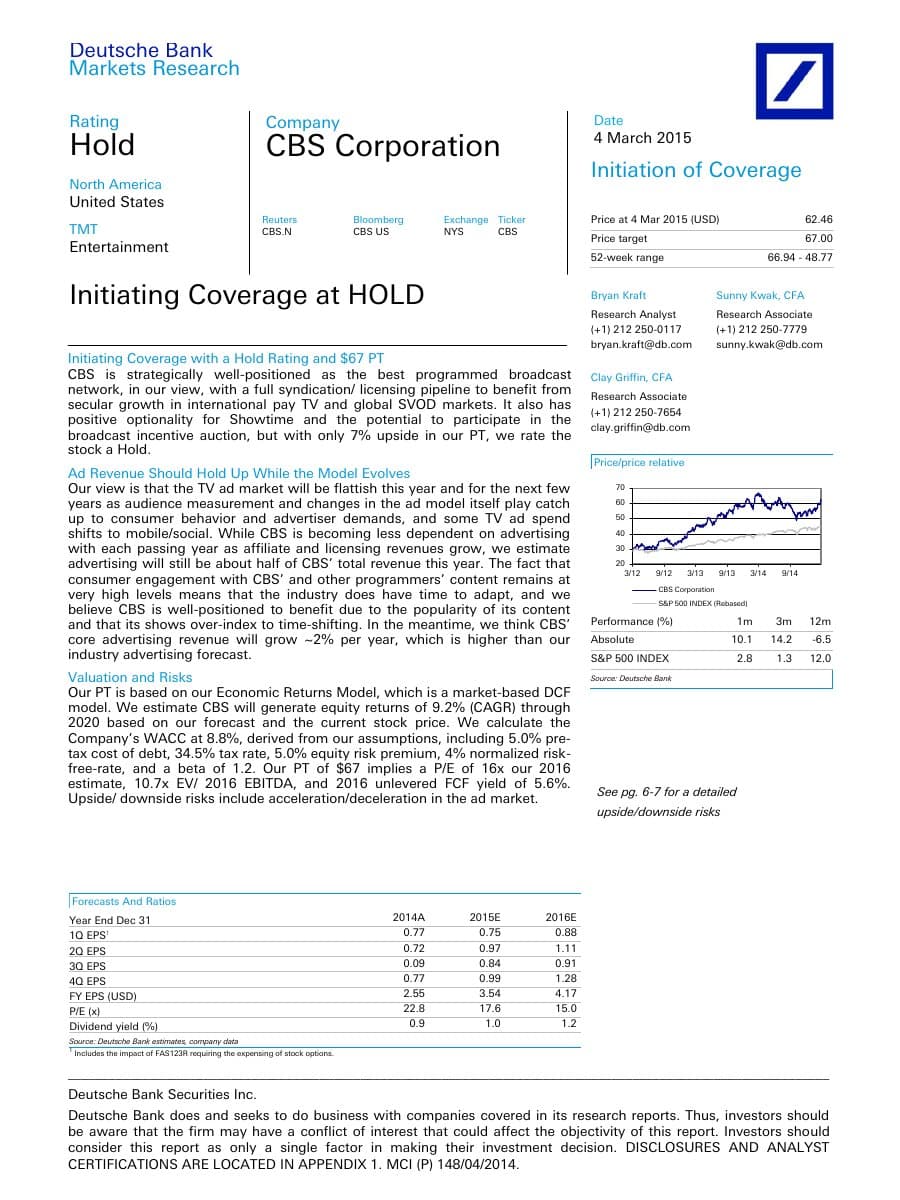
- CBSDeutsche BankHow the same valuation framework yields a Hold when upside to target is only 7%, and how ad exposure caps a broadcaster's multiple.Initiation of coverage · March 4, 2015 · 16 pagesTarget USD 67.00
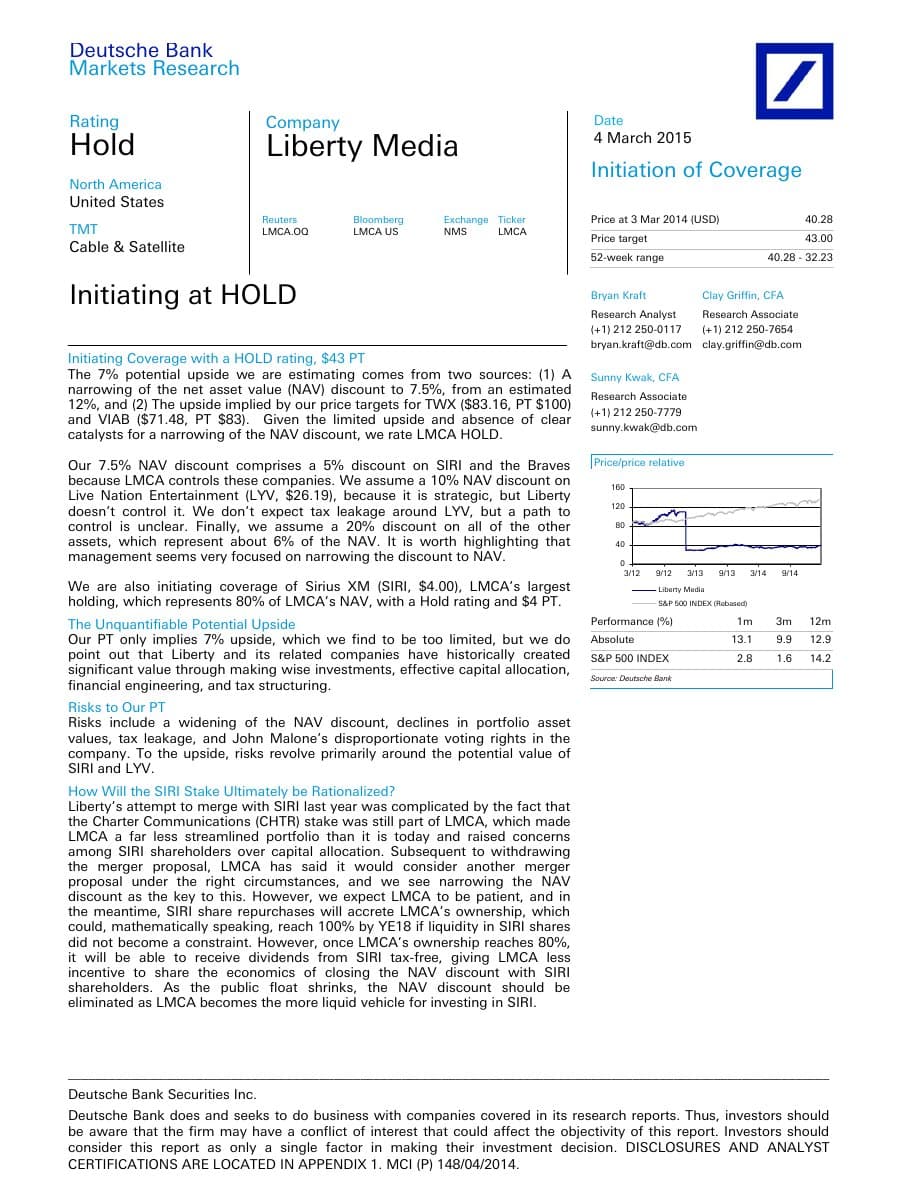
- Liberty MediaDeutsche BankHow to value a holding company by summing its stakes at a discount to net asset value based on control and liquidity.Initiation of coverage · March 4, 2015 · 11 pagesTarget USD 43.00
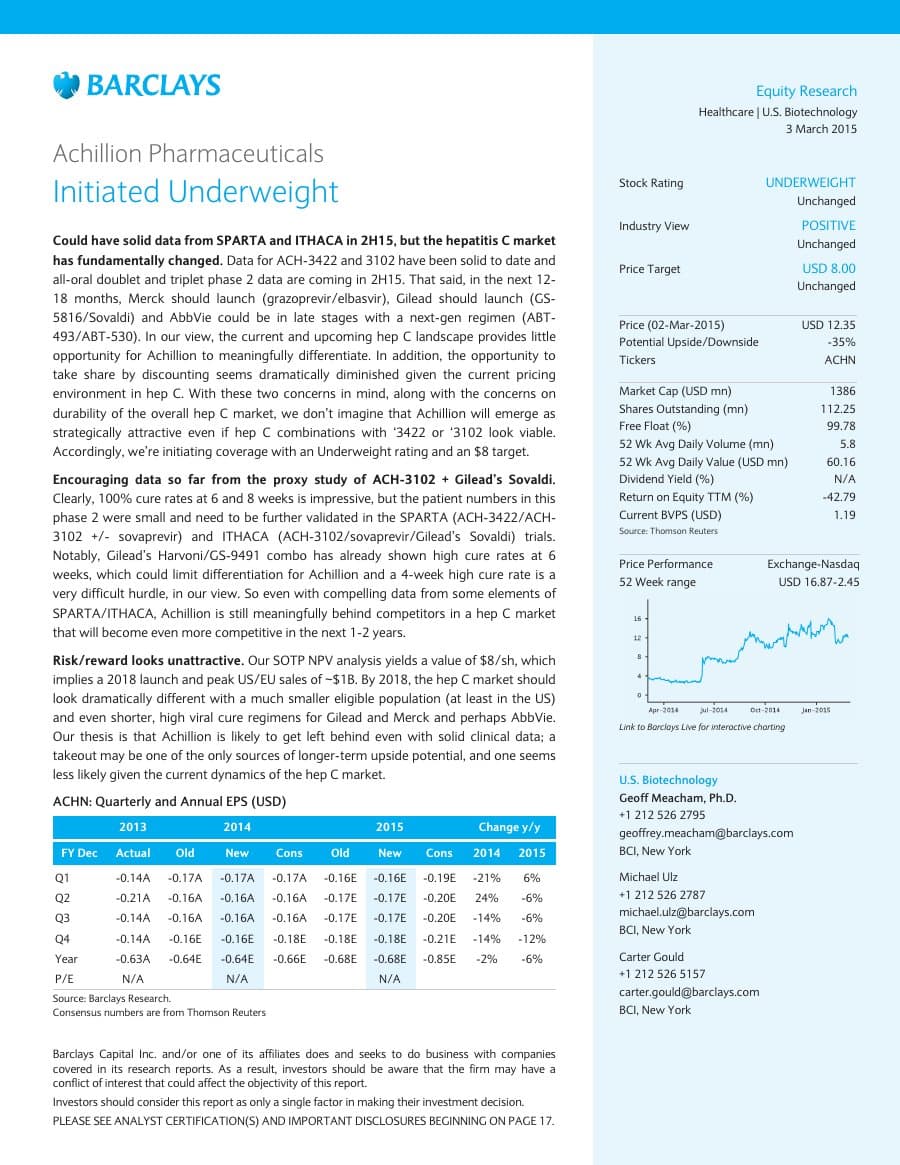
- Achillion PharmaceuticalsBarclaysHow a biotech analyst values a pre-revenue drug pipeline with a risk-adjusted NPV sum-of-the-parts and a competitive launch timeline.Initiation of coverage · March 3, 2015 · 23 pagesTarget USD 8.00