Imperial Oil
How a short post-event note blends a NAV and a cash flow multiple, and lays out upside and downside scenarios.
- Rating
- Price target
- CAD 48.00
- Published
- June 13, 2013
- Length
- 11 pages
- Sector
- Integrated oil
- Market
- Canada
What the analyst argued
RBC's investor-day note kept Imperial Oil at Sector Perform and trimmed the target to C$48 from C$49, reflecting lower Kearl oil sands volumes. The analysts noted Imperial's shift toward multi-year upstream growth, its plan to use rail as insurance against Keystone XL delays, and the arrival of ExxonMobil veteran Rich Kruger as CEO. They argued the company's premium debt-adjusted cash flow multiple (1.7-1.9x above Canadian integrated peers) could erode as cost overruns at Kearl pulled its 23% ROACE lower. The target blended 1.1x a DCF-based net asset value (60%) with a 10.3x 2014E debt-adjusted cash flow multiple (40%).
Lead analysts: Greg Pardy, Dillon Culhane, Carson Tong.
Inside the report
- 01Investment Thesis
- 02Target/Upside/Downside Scenarios
- 03Upstream Growth Abounds
- 04Kearl Marketing Strategy
- 05Revised Estimates
- 06Operating and Financial Summary
- 07Valuation
- DCF
- P/E
- Comparable companies
Includes a multi-year earnings model with the income statement, balance sheet, and cash flow forecasts the valuation is built on.
Read the report
11 pages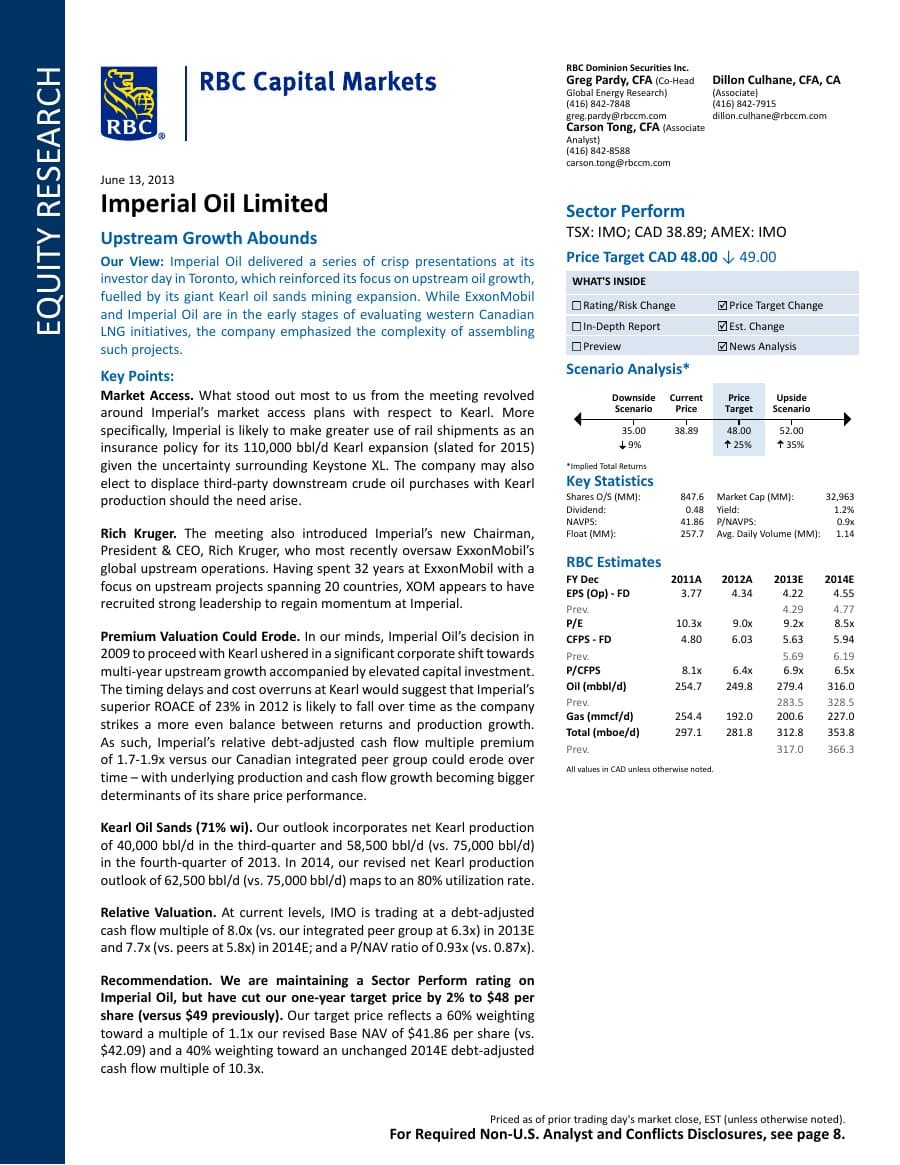 Tap the cover to open the PDF.
Published by RBC Capital Markets on June 13, 2013 and hosted here for educational use; the report and everything in it belongs to RBC Capital Markets. The rating, estimates, and price target are the analysts’ view on that date, more than a decade ago, and are not a recommendation today. Copy first uploaded October 5, 2026.
More update notes
20 reports in the library- KEYWSunTrust Robinson HumphreyHow an earnings update separates a near-term estimate cut from an unchanged thesis, and values a small-cap on forward EV/EBITDA.Update note · April 30, 2013 · 7 pagesTarget USD 18.00
- Crescent Point EnergyBMO Capital MarketsHow E&P analysts value a dividend-paying producer on debt-adjusted cash flow multiples cross-checked against a reserves-based NAV.Update note · August 9, 2013 · 14 pagesTarget CAD 48.00