Duke Energy
How credit analysts compare holdco and opco bonds on g-spread and FFO/debt, and spot a bond-CDS basis trade.
- Rating
- Price target
- None given
- Published
- January 5, 2015
- Length
- 17 pages
- Sector
- Utilities credit
- Market
- US
What the analyst argued
Goldman's credit team initiated on the Duke complex, rating Duke Energy Corp and its operating companies In-Line because tight spreads were justified by scale, favourable regulation and an improving profile after the Midwest merchant sale. It rated intermediate holdco Progress Energy Underperform: its bonds had converged with Duke's after historically trading 10-15bp wider, yet Progress was less diversified and covered interest from subsidiary dividends only 1.8x versus more than 3x at Duke. The note also recommended a bond/CDS negative basis trade and discussed what would trigger an S&P upgrade.
Lead analysts: Erin Blum, Sean Hanley.
Inside the report
- 01Recommendation
- 02Summary Relative Value
- 03Summary investment theses
- 04DUK CDS - bond/CDS basis trade is attractive
- 05Utility holdco and opco relative value
- 06Trading trends
- 07Business profile and regulatory environment
- 08Cash deployment and ratings outlook
- 09International business is higher risk
- 10Capital Structure and Summary Financials
- Credit spreads
- Comparable companies
Valuation methods the analyst leans on. This note updates an existing model rather than printing the full forecast.
Read the report
17 pages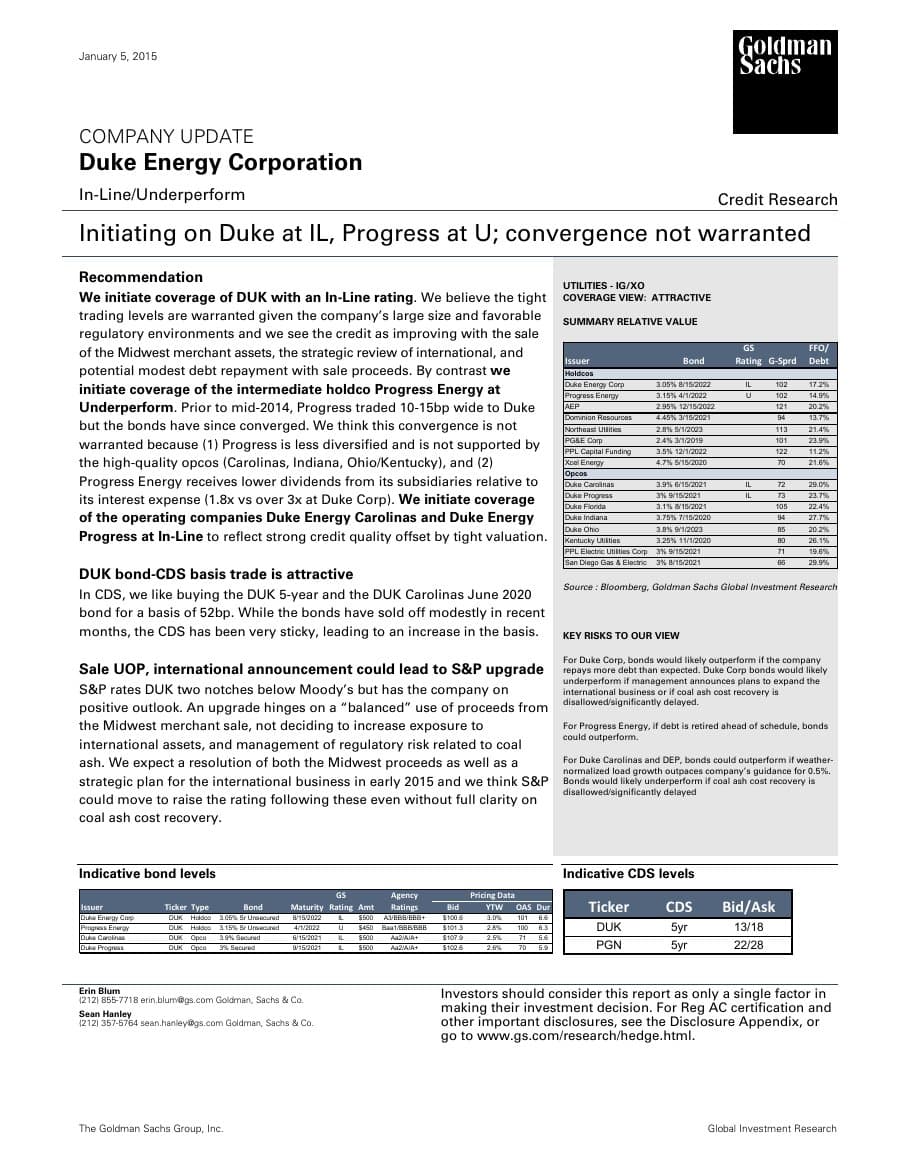 Tap the cover to open the PDF.
Published by Goldman Sachs on January 5, 2015 and hosted here for educational use; the report and everything in it belongs to Goldman Sachs. The rating, estimates, and price target are the analysts’ view on that date, more than a decade ago, and are not a recommendation today. Copy first uploaded October 5, 2026.
More initiations
20 reports in the library- CGN PowerDeutsche BankHow to build a life-of-asset DCF with no terminal value for a utility, and how to argue Sell on a well-liked IPO.Initiation of coverage · January 7, 2015 · 55 pagesTarget HKD 2.90
- 3P LearningDeutsche BankHow to value a recently listed subscription software company with a DCF, then stress-test it with bull and bear scenarios.Initiation of coverage · January 14, 2015 · 44 pagesTarget AUD 2.70
- Virgin Money HoldingsGoldman SachsHow bank analysts turn a return-on-tangible-equity forecast into a price-to-book multiple via the ROTE/COE framework.Initiation of coverage · December 23, 2014 · 44 pagesTarget 320p
- Australian Aged CareDeutsche BankHow a sector initiation models demographics and government funding before comparing three operators on the same DCF framework.Sector initiation · January 23, 2015 · 126 pagesTarget AUD 5.90 Estia, 4.50 Regis, 2.12 Japara