ABB
How analysts frame a conglomerate initiation around four pillars: growth, secular trends, profitability, and sentiment.
- Rating
- Price target
- CHF 21.00
- Published
- March 12, 2015
- Length
- 24 pages
- Sector
- Industrials
- Market
- Europe
What the analyst argued
Nomura initiated ABB at Neutral with a CHF 21 target as part of a sector report on the industrial internet. ABB scored well on secular trends thanks to its leadership in process and factory automation software and the 'Next Level' strategy, and its cost-savings record was credible. But more than 10% of sales were exposed to oil and gas, and power and mining markets stayed weak, putting Nomura's revenue forecasts below consensus; three years of earnings disappointments had already erased the valuation premium, so the risk/reward was balanced.
Lead analysts: Alexander Virgo, Maggie Paxton, Felix Wienen.
Inside the report
- 01Key data on ABB
- 02Downside revenue risks from O&G
- 03Standing at the forefront of industrial software development
- 04Growing service revenue has been difficult after a strong start
- 05Regional balance cuts both ways
- 06Oil & gas exposure and capex forecasts
- 07Cost savings and profitability
- 08Valuation premium has disappeared
- 09Our forecasts relative to consensus
- 10Fiscal Headline Data and Cash Flow
- DCF
- Sum-of-the-parts
- P/E
- EV/EBITDA
- Comparable companies
Includes a multi-year earnings model with the income statement, balance sheet, and cash flow forecasts the valuation is built on.
Read the report
24 pages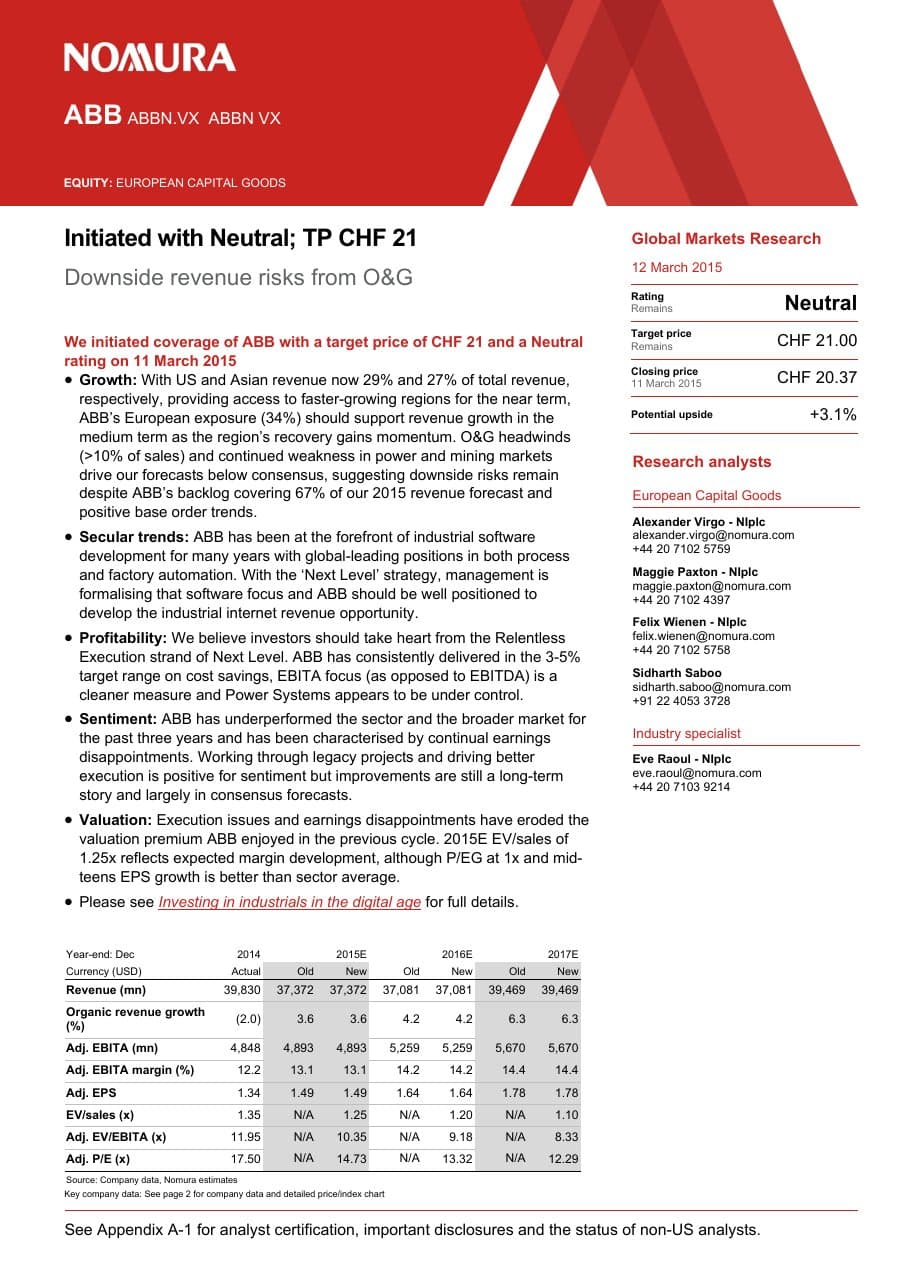 Tap the cover to open the PDF.
Published by Nomura on March 12, 2015 and hosted here for educational use; the report and everything in it belongs to Nomura. The rating, estimates, and price target are the analysts’ view on that date, more than a decade ago, and are not a recommendation today. Copy first uploaded October 5, 2026.
More initiations
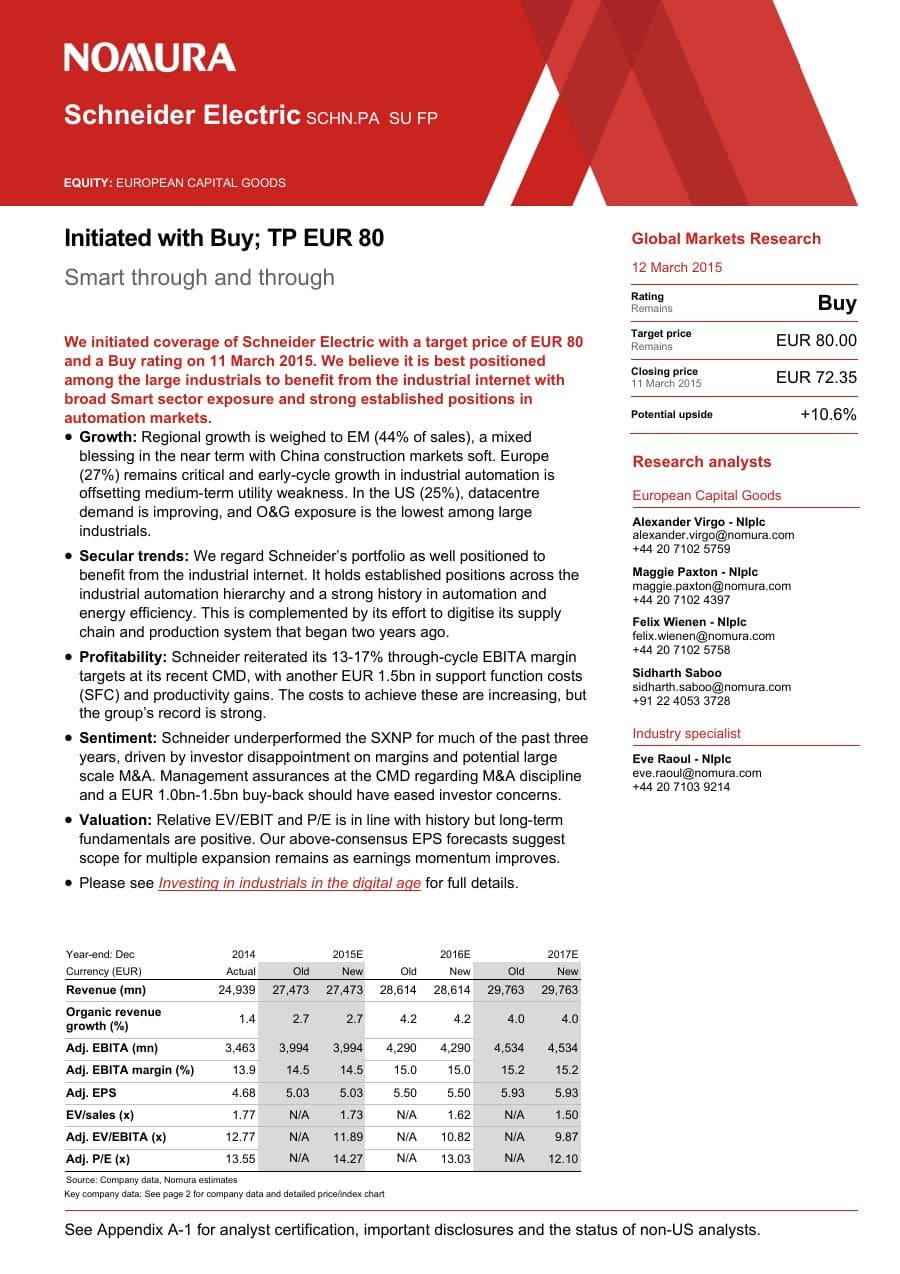
20 reports in the library- Schneider ElectricNomuraHow a thematic sector view on the industrial internet becomes a stock-specific Buy with a target blended from multiples and a DCF.Initiation of coverage · March 12, 2015 · 21 pagesTarget EUR 80.00
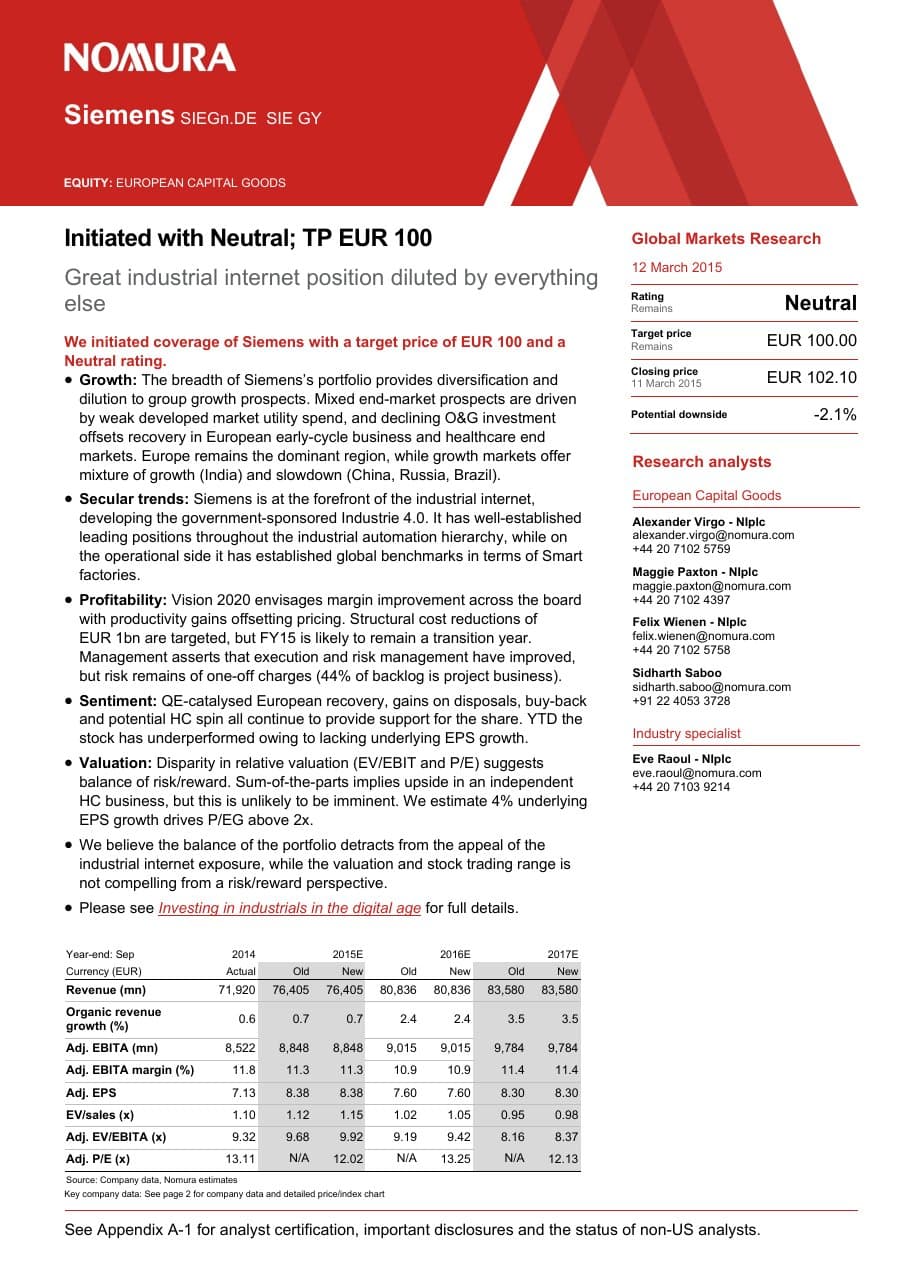
- SiemensNomuraHow a sum-of-the-parts valuation separates a conglomerate's segments and why a strong division may not lift the whole stock.Initiation of coverage · March 12, 2015 · 22 pagesTarget EUR 100.00
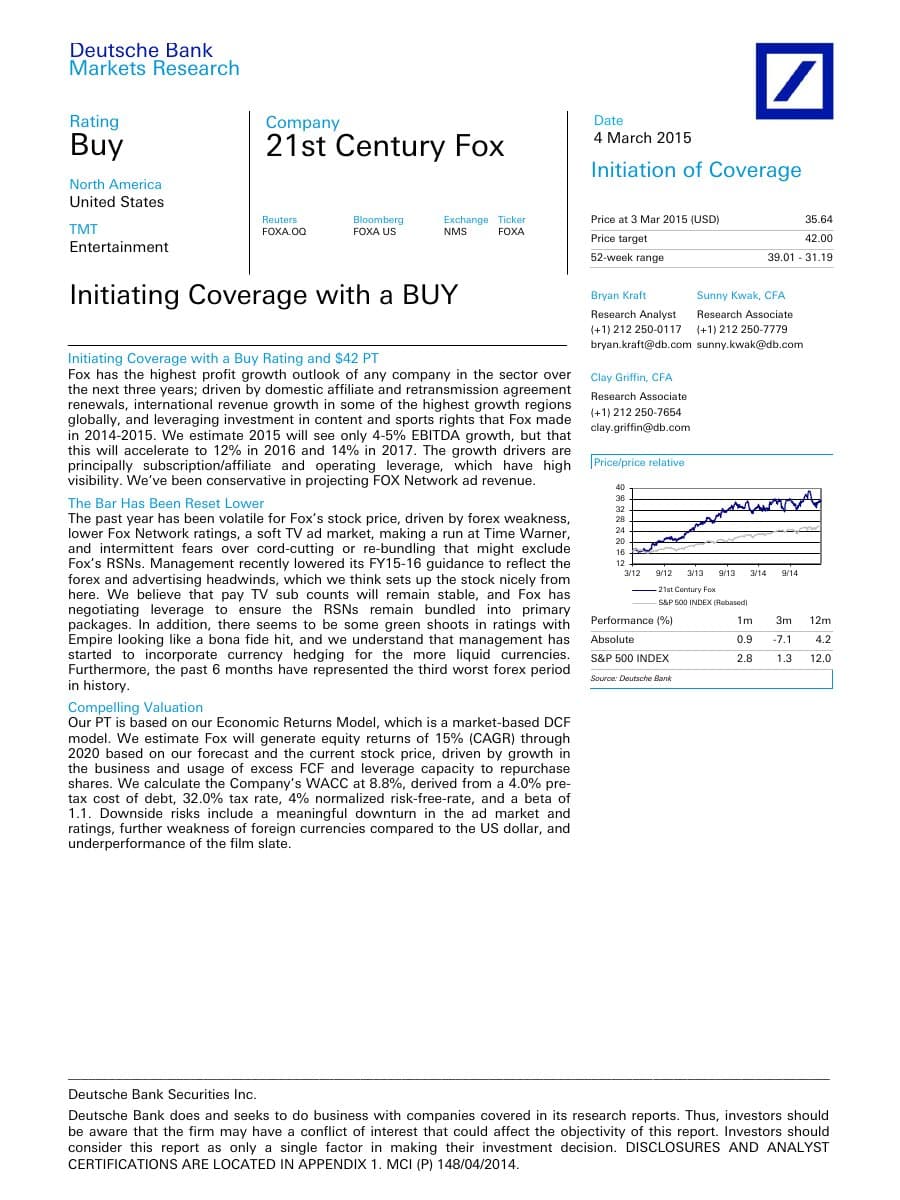
- 21st Century FoxDeutsche BankHow Deutsche Bank's Economic Returns Model, a market-based DCF, turns a WACC and a free cash flow yield into an implied equity return.Initiation of coverage · March 4, 2015 · 17 pagesTarget USD 42.00
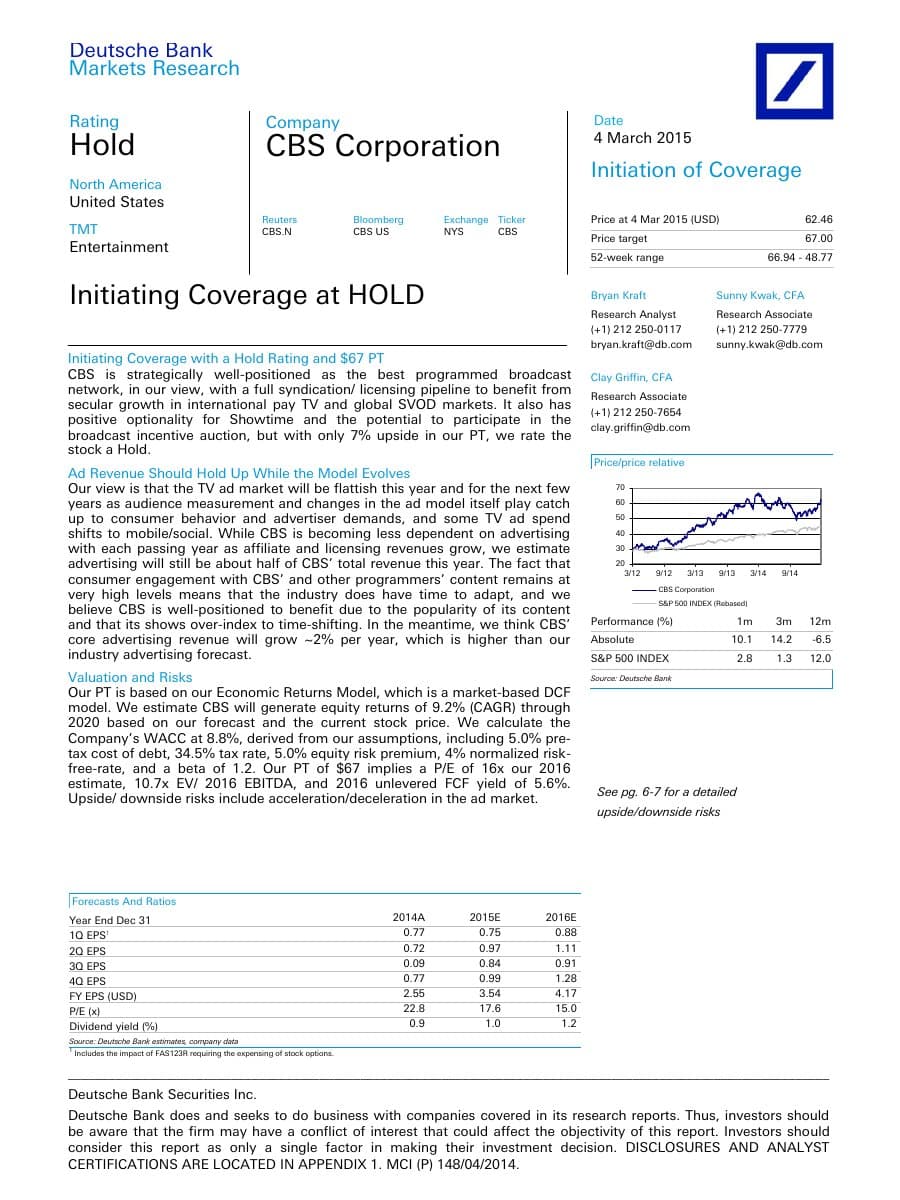
- CBSDeutsche BankHow the same valuation framework yields a Hold when upside to target is only 7%, and how ad exposure caps a broadcaster's multiple.Initiation of coverage · March 4, 2015 · 16 pagesTarget USD 67.00